
Principles of Double Entry – SS1 Book Keeping Lesson Note (Second Term)
Download this term · ₦1,000Lesson note at a glance
- Subject
- Book Keeping
- Class
- SS1
- Term
- Second Term
- Topic
- Principles of Double Entry
- Order
- Topic 2 of 6 this term
- Reading time
- 4 min
The principle of double entry states that every transaction has two equal effects, so every debit entry must have a matching credit entry.
- Foundation: it is the basis of the whole bookkeeping system.
- Two aspects: every transaction has a receiver, whose account is debited, and a giver, whose account is credited.
- Double entry: recording each business transaction twice in the books of account, once as a debit and once as a credit.
Behavioural objectives
By the end of the lesson, students should be able to:
- State the principle of double entry.
- Identify the receiver (debit) and the giver (credit) in a transaction.
- List the benefits of double entry.
- State the effect of a transaction on the accounts involved.
- Name the account to debit and the account to credit for a given transaction.
What is the principle of double entry?
The principle of double entry states that for every debit entry there must be a corresponding credit entry, and the other way round.
- Debit (Dr): the account that receives value, the receiver.
- Credit (Cr): the account that gives value, the giver.
- Equal amounts: the debit entry and the credit entry for a transaction are always the same amount.
- Two accounts: at least two accounts are affected by every transaction.
What is a ledger account?
A ledger account is a record that collects all transactions of one kind, such as cash, rent or capital.
- Left side: the debit side.
- Right side: the credit side.
- Account name: written at the top, for example Cash account.
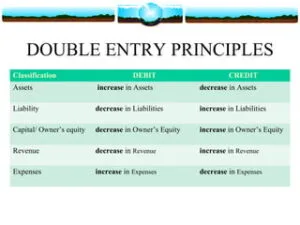
What are the rules for debit and credit?
The rule depends on the type of account and on whether the account increases or decreases.
| Type of account | Increase | Decrease | Example |
|---|---|---|---|
| Asset | Debit | Credit | Cash, Bank, Office Equipment |
| Liability | Credit | Debit | Loan from Chinaza |
| Capital | Credit | Debit | Owner’s capital |
| Expense | Debit | Credit | Rent, Wages |
| Income | Credit | Debit | Sales, Commission received |
| Drawings | Debit | Credit | Cash or goods taken for private use |
How do you apply double entry to a transaction?
Apply double entry by finding the two accounts affected and deciding which one receives and which one gives.
- Read the transaction and identify the two accounts affected.
- State the type of each account: asset, liability, capital, expense, income or drawings.
- State whether each account increases or decreases.
- Use the rules to decide the account to debit (receiver).
- Decide the account to credit (giver).
- Check that both entries have the same amount.
What are the benefits of double entry?
Double entry gives a complete and checkable record of every transaction in a business.
- Complete records: both aspects of every transaction are recorded.
- Fewer frauds and easier correction of errors: each entry has a matching entry, so mistakes and false entries are easier to trace.
- Test of arithmetical accuracy: the total of debits must equal the total of credits, as checked in a trial balance.
- Financial information: it supplies the figures used to prepare financial statements.
- Internal control: it helps an organisation apply and review its internal control system.
What is an illustration of the principle of double entry?
For each transaction below, identify the effect on the accounts, then decide which account receives (debit) and which account gives (credit).
| Date | Transaction | Effect | Debit (receiver) | Credit (giver) |
|---|---|---|---|---|
| Jan 1 | Mr Chidera started the business with ₦10,000 | Increase in capital: Capital account Increase in asset: Cash account |
Cash account | Capital account |
| Jan 2 | Paid ₦450 cash for rent | Increase in expense: Rent account Decrease in asset: Cash account |
Rent account | Cash account |
| Jan 3 | Bought office equipment ₦600,000 by cheque | Increase in asset: Office Equipment account Decrease in asset: Bank account |
Office Equipment account | Bank account |
| Jan 8 | Withdrew cheque for private use ₦2,000 | Increase in drawings: Drawings account Decrease in asset: Bank account |
Drawings account | Bank account |
| Jan 9 | Withdrew ₦600 cash from the bank for office use | Increase in asset: Cash account Decrease in asset: Bank account |
Cash account | Bank account |
| Jan 10 | Received loan of ₦20,000 cash from Chinaza | Increase in asset: Cash account Increase in liability: Loan account |
Cash account | Loan account |
Worked example: Jan 2, rent paid in cash
- Rent account: debit ₦450, because the business receives the benefit of the rent (an expense).
- Cash account: credit ₦450, because cash goes out of the business (an asset decreases).
What mistakes do students make in double entry?
- Using “debit means decrease”: a debit increases an asset or expense but decreases a liability or capital.
- Entering only one side: every transaction needs a debit and a credit.
- Unequal amounts: the debit and the credit must be the same figure.
- Mixing drawings with expenses: money taken for private use goes to Drawings, not to an expense account.
Evaluation
- State the principle of double entry.
- Which account is debited and which is credited in a transaction?
- List any three benefits of double entry.
- Mr Chidera paid ₦450 cash for rent. State the effect of this transaction and the accounts to debit and credit.
- Chinaza gave the business a loan of ₦20,000 in cash. Which account is the receiver and which is the giver?
Assignment
Define double entry in your own words. Then take the transaction of Jan 8 (withdrew cheque for private use ₦2,000) and state its effect, the account to debit and the account to credit.
This term's Book Keeping topics
SS1 Second Term · 6 topics
- Books of Original Entry
- Principles of Double Entry
- Ledgers
- Single Column Cash Book
- Double Column Cash Book
- Contra Entries
Get Book Keeping as PDF and Word
Every week of SS1 Book Keeping, Second Term, formatted and ready to print. Ad-free, and the copy lock comes off.
Get this term Card, bank transfer, USSD or OPay
SS1 Book Keeping Lesson Notes for Other Topics
Books Of Original Entry
Read the full lesson note.
Ledgers
Read the full lesson note.
Single Column Cash Book
Read the full lesson note.

Double Column Cash Book
Read the full lesson note.
Contra Entries
Read the full lesson note.
Introduction To Bookkeeping
Read the full lesson note.
Stock Valuation
Read the full lesson note.

Assets And Liabilities
Read the full lesson note.
Business Transactions
Read the full lesson note.
Debtors And Creditors
Read the full lesson note.
Source Documents
Read the full lesson note.
Three Column Cash Book
Read the full lesson note.
Petty Cashbook
Read the full lesson note.
Trial Balance
Read the full lesson note.
Lesson Notes for Other Classes

SS2 Lesson Note
The complete lesson note to guide your studies.

SS3 Lesson Note
The complete lesson note to guide your studies.
