
Balance Sheet – SS2 Financial Accounting Lesson Note (Third Term)
Download this term · ₦1,000Lesson note at a glance
- Subject
- Financial Accounting
- Class
- SS2
- Term
- Third Term
- Topic
- Balance Sheet
- Order
- Topic 3 of 5 this term
- Reading time
- 4 min
The Balance Sheet is a statement of the financial position of a business on a certain date. It shows the assets, liabilities and capital of the business in a well-arranged form.
Behavioural objectives
By the end of the lesson, students should be able to:
- state what a Balance Sheet is and say why it is called a position statement;
- list the headings under which items are grouped in a Balance Sheet;
- arrange fixed assets and current assets in the correct order;
- define assets and liabilities and classify each into its types, with examples;
- name the two formats of the Balance Sheet and state the main advantage of the vertical format.
What is a Balance Sheet?
Unlike a Trading, Profit and Loss Account, a Balance Sheet is not part of the double entry system. After the nominal account balances have been transferred to the Trading and Profit and Loss Account, the only balances left in the ledger are those for assets and liabilities. The Balance Sheet is a list of these balances.
Although a Balance Sheet is not an account, the Trading and Profit and Loss Account and the Balance Sheet are known collectively as the final accounts of a business.
Layout of the Balance Sheet
The Balance Sheet is prepared by listing and grouping the assets and liabilities of the business under appropriate headings, as below:
- Fixed Assets
- Current Assets
- Current Liabilities
- Long-term Liabilities
- Capital
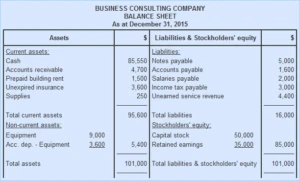
Points to note
- A Balance Sheet is a ‘position’ statement showing the position of a business at a particular date. It is not a ‘period’ statement like a Trading and Profit and Loss Account.
- The fixed assets are listed in order of permanence. For example:
- Land and Buildings
- Plant and Machinery
- Furniture and Fittings
- Equipment/Tools
- Motor Vehicles
- The current assets are listed in the reverse order of realisability, i.e. the ease with which they can be converted to cash. The order is:
- Stock
- Debtors
- Bank
- Cash
At the end of the year, the balances on the Profit and Loss Account and Drawings Account are transferred to the Capital Account (by Journal entries). However, the details are still shown in the Balance Sheet to show how the closing capital is arrived at.
What are the items in a Balance Sheet?
Assets
Assets are the resources, properties or possessions owned by the business, as well as what other people or firms owe the business. Examples are Land and Buildings, Motor Vehicles, Furniture, Equipment, Machinery, Tools, Stock, Cash at hand, Cash at Bank, Debtors etc. Assets can be divided into fixed assets and current assets.
Fixed Assets are long-lasting assets which are acquired for use rather than for resale. Fixed assets help the business to earn revenue. Examples are Land and Buildings, Plants, Machinery, Motor Vehicles, Furniture, Fittings, Tools, Equipment etc.
Current Assets are assets which are usually held by the business for a short period. They are usually converted from one form to another in the course of business. Current assets are either in the form of cash or can be turned into cash relatively easily. Examples are Stock (Inventory), Trade Debtors (or Sundry Debtors), Bank and Cash.
Liabilities
Liabilities are obligations arising from past transactions. A liability is a claim by outsiders on the assets of the business. Liabilities represent what the business owes other people or firms. They can be classified as current liabilities and long-term liabilities.
Current Liabilities are short-term liabilities. They are the amounts owed by the business which are due for settlement (repayment) within the next twelve months (i.e. one year) of the date of the Balance Sheet. Examples are Trade Creditors (or Sundry Creditors), Bank Overdrafts etc.
Long-term Liabilities are amounts owed by the business which are not due for repayment within the next twelve months (i.e. one year) of the date of the Balance Sheet. Examples are Long-term loans, Mortgages, Debentures etc.
What are the formats of a Balance Sheet?
The Balance Sheet can be prepared in two ways: horizontal format and vertical format. The Balance Sheet earlier prepared for Ade Molayo was prepared in the horizontal format.
NB: The main advantage a vertical Balance Sheet has over a horizontal Balance Sheet is that it shows the figure for the net current assets. This is also known as the working capital.
Evaluation
- What is a Balance Sheet?
- Explain the difference between a ‘position’ statement and a ‘period’ statement.
- List the five headings under which items are grouped in a Balance Sheet.
- Distinguish between fixed assets and current assets, giving two examples of each.
- State the main advantage of a vertical Balance Sheet over a horizontal one.
Assignment
- List the current assets in the order in which they appear in a Balance Sheet, and explain why they are arranged in that order.
- Explain the difference between current liabilities and long-term liabilities, giving two examples of each.
This term's Financial Accounting topics
SS2 Third Term · 5 topics
Get Financial Accounting as PDF and Word
Every week of SS2 Financial Accounting, Third Term, formatted and ready to print. Ad-free, and the copy lock comes off.
Get this term Card, bank transfer, USSD or OPay
SS2 Financial Accounting Lesson Notes for Other Topics
Dissolution Of Partnership
Read the full lesson note.
Company Accounts
Read the full lesson note.
Issues & Classes of Shares
Read the full lesson note.
Interpretation Of Financial Statement Using Simple Ratio
Read the full lesson note.

Suspense Account
Read the full lesson note.
Suspense Account II - Correction of Errors
Read the full lesson note.
Manufacturing Accounts
Read the full lesson note.
Control Account And Self-Balancing Ledger
Read the full lesson note.
Introduction To Single Entry And Incomplete Records
Read the full lesson note.

Single Entry And Incomplete Records
Read the full lesson note.
Accounts Of Non Profit Making Organisations
Read the full lesson note.
Partnership Accounts
Read the full lesson note.
Partnership Accounts II - Partnership Capital Accounts & How to Calculate it
Read the full lesson note.

Receipts And Payment Accounts
Read the full lesson note.
Lesson Notes for Other Classes
SS1 Lesson Note
The complete lesson note to guide your studies.
SS3 Lesson Note
The complete lesson note to guide your studies.
