
Single Entry and Incomplete Records – SS2 Financial Accounting Lesson Note (Second Term)
Lesson note at a glance
- Class
- SS2
- Subject
- Financial Accounting
- Term
- Second Term
- Reading time
- 7 min
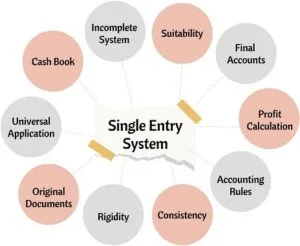
Incomplete records (single entry) is a way of keeping accounts without full double entry, so the business has only some records, mainly of cash and bank receipts and payments. A profit and loss account and a balance sheet can still be prepared from them by following set steps.
Behavioural objectives
- Name the records a business may keep when it does not use full double entry.
- List the six steps for preparing a P&L A/C and balance sheet from incomplete records.
- Prepare an opening statement of affairs to find the opening capital.
- Explain why control accounts for debtors and creditors are prepared.
- Prepare a P&L A/C and balance sheet from a set of incomplete records.
What records do businesses keep under incomplete records?
A business using incomplete records usually keeps six main records, mostly of cash, bank, debtors and creditors.
- Bank paying-in book counterfoils: show the money the business paid into the bank.
- Chequebook counterfoils: show the cheques the business drew and what each was for.
- Bank statements: show the bank’s record of all receipts and payments.
- Supplier invoices: show goods bought on credit.
- Copies of sales invoices: show goods sold on credit.
- Lists of debtors and creditors: show who owes the business and whom the business owes.
What are the limits of incomplete records?
The main limit of incomplete records is that profit is worked out from available figures and not taken from ledger accounts.
- No trial balance: the accuracy of the records cannot be checked this way.
- Missing figures: sales and purchases must be calculated.
- Errors: they are hard to find.
- Typical users: small traders, such as a market stall owner.
How does incomplete records differ from double entry?
Incomplete records record mostly cash and bank items. Double entry gives every transaction a debit and a credit.
| Point | Incomplete records | Double entry |
|---|---|---|
| Entries | Mostly cash and bank items only | Every transaction has a debit and a credit |
| Trial balance | Cannot be prepared | Can be prepared to check accuracy |
| Profit | Must be worked out from the available figures | Found from the ledger accounts |
| Errors | Hard to find | Easier to find |
| Users | Small traders, such as a market stall owner | Most businesses |
What is a statement of affairs?
A statement of affairs is a list of the assets and liabilities of a business on a given date.
- Use: it gives the capital of the business on that date.
- Formula: Capital = Total assets – Total liabilities.
- Opening statement of affairs: prepared at the start of the period to find the opening capital.
- Closing statement of affairs: prepared at the end of the period to find the closing capital.
Worked example: opening capital
| Item | Type | Amount (N) |
|---|---|---|
| Shop fittings | Asset | 2000 |
| Stock | Asset | 1500 |
| Debtors | Asset | 300 |
| Bank and cash | Asset | 800 |
| Total assets | 4600 | |
| Creditors | Liability | 400 |
| Opening capital | 4600 – 400 | 4200 |
How is profit found from the change in capital?
Profit is the closing capital minus the opening capital, adjusted for drawings and capital introduced.
- Formula: Profit = Closing capital – Opening capital + Drawings – Capital introduced during the year.
- Drawings: money or goods the owner takes for personal use. They are added back because they reduced the capital.
- Capital introduced: extra money the owner puts in. It is deducted because it increased the capital but is not profit.
- Example: closing capital N5000, opening capital N4200, drawings N900, capital introduced N200.
- Answer: Profit = 5000 – 4200 + 900 – 200 = N1500.
What are the steps in preparing a P&L A/C and balance sheet from incomplete records?
There are six steps, taken in this order.
- Prepare an opening statement of affairs (to obtain the opening capital).
- Prepare a receipts and payments A/C.
- Prepare control A/Cs for debtors and creditors, if necessary, to calculate sales and purchases. The sales and purchases figures are needed to make the accounts balance.
- Adjust the receipts and payments account for prepayments and accruals at the beginning and end of the period.
- Calculate provisions for doubtful debts, depreciation and any other matters not mentioned above.
- Prepare the P&L A/C and Balance Sheet from the information now available.
Why are control accounts prepared?
Control accounts are prepared to find sales and purchases, because these figures are not recorded directly.
- Debtors control account: finds the credit sales for the period.
- Creditors control account: finds the credit purchases for the period.
What is a debtors control account?
A debtors control account is an account that brings together all debtors to find the credit sales for the period.
- Debit side: opening debtors and credit sales (the missing figure).
- Credit side: cash and cheques received from debtors, and closing debtors.
- Formula: Credit sales = Cash received from debtors + Closing debtors – Opening debtors.
- Example: opening debtors N500, cash received N4200, closing debtors N700.
- Answer: Credit sales = 4200 + 700 – 500 = N4400.
What is a creditors control account?
A creditors control account is an account that brings together all creditors to find the credit purchases for the period.
- Credit side: opening creditors and credit purchases (the missing figure).
- Debit side: cash and cheques paid to creditors, and closing creditors.
- Formula: Purchases = Payments to creditors + Closing creditors – Opening creditors.
- Example: opening creditors N300, payments N2500, closing creditors N400.
- Answer: Purchases = 2500 + 400 – 300 = N2600.
How are total sales found?
Total sales are cash sales plus credit sales.
- Total sales: cash sales plus credit sales.
- Takings: if takings are banked after cash payments, add back those cash payments to find the full takings.
- Example: takings banked N5000 after cash payments of N300 gives full takings of N5300.
How are expenses adjusted for prepayments and accruals?
Expenses are adjusted so that the P&L A/C shows only the expense that belongs to the period.
- Prepayment: an expense paid before the period it belongs to, such as rent paid in advance. It is a current asset with a debit balance.
- Accrual: an expense used but not yet paid, such as electricity owing. It is a current liability with a credit balance.
- Expense with prepayment: Amount paid + Opening prepayment – Closing prepayment.
- Expense with accrual: Amount paid – Opening accrual + Closing accrual.
- Result: the figure found goes to the P&L A/C. The closing prepayment or accrual goes to the balance sheet.
- Prepayment example: rent paid N1000, opening prepayment N100, closing prepayment N150. Rent expense = 1000 + 100 – 150 = N950.
- Accrual example: wages paid N500, opening accrual N100, closing accrual N150. Wages expense = 500 – 100 + 150 = N550.
What other items must be calculated?
Provision for doubtful debts and depreciation are the other items worked out before the final accounts.
- Provision for doubtful debts: an amount set aside for debts that may not be paid. It is charged in the P&L A/C.
- Depreciation: the fall in value of a fixed asset, such as shop fittings, through use. It is charged in the P&L A/C.
- Step: these are done in step 5, before the final accounts are prepared.
Evaluation
- A debtors control account is prepared mainly to find: (a) debtors (b) creditors (c) cash received (d) sales.
- In incomplete records, a creditors’ control account is prepared mainly to find: (a) sundry creditors (b) purchases (c) cash paid to creditors (d) discount received.
- In adjustment accounts, the prepaid rent A/C should have a ______ balance: (a) credit (b) debit (c) both debit and credit (d) either debit or credit.
- In adjusting for final accounts, accrued wages should have a ______ balance: (a) debit (b) credit (c) debit and credit (d) debit or credit.
- The calculation of provisions for doubtful debts, depreciation and similar items is done in step ____ when preparing the P&L A/C and balance sheet from incomplete records: (a) 1 (b) 2 (c) 5.
Assignment
Azim keeps only bank pay-in-book counterfoils, chequebook counterfoils and records of debtors and creditors. Use the facts below to prepare his profit and loss account for the year ended 31 December 2003 and his Balance Sheet at that date.
Bank summary for the year ended 31/12/03
- Takings paid into the bank: N8000.
- Cheques to suppliers: N2430.
- Rent: N600.
- Electricity: N320.
- Postage and stationery: N80.
- Shop fittings bought: N480.
- Personal expenses (drawings): N2700.
Cash payments made before banking the takings
- Creditor for supplies: N400.
- Sundry expenses: N115.
Assets and liabilities
| Item | 1 January 2003 (N) | 31 December 2003 (N) |
|---|---|---|
| Shop fittings | 1600 | 1800 |
| Stock | 1960 | 1520 |
| Debtors | 240 | 380 |
| Rent prepaid | 80 | 50 |
| Bank balance | 1500 | 2640 |
| Cash in hand | 50 | 50 |
| Creditors for goods | 420 | 390 |
| Electricity owing | 130 | 225 |
This term's Financial Accounting topics
SS2 Second Term · 5 topics
SS2 Financial Accounting Lesson Notes for Other Topics
Accounts Of Non Profit Making Organisations
Read the full lesson note.
Partnership Accounts
Read the full lesson note.
Partnership Accounts II - Partnership Capital Accounts & How to Calculate it
Read the full lesson note.

Receipts And Payment Accounts
Read the full lesson note.

Suspense Account
Read the full lesson note.
Suspense Account II - Correction of Errors
Read the full lesson note.
Manufacturing Accounts
Read the full lesson note.
Control Account And Self-Balancing Ledger
Read the full lesson note.
Introduction To Single Entry And Incomplete Records
Read the full lesson note.
Dissolution Of Partnership
Read the full lesson note.
Company Accounts
Read the full lesson note.
Balance Sheet
Read the full lesson note.
Issues & Classes of Shares
Read the full lesson note.
Interpretation Of Financial Statement Using Simple Ratio
Read the full lesson note.
Lesson Notes for Other Classes

SS1 Lesson Note
The complete lesson note to guide your studies.

SS3 Lesson Note
The complete lesson note to guide your studies.
