
Acquisition/Purchase of Business – SS3 Financial Accounting Lesson Note (First Term)
Lesson note at a glance
- Class
- SS3
- Subject
- Financial Accounting
- Term
- First Term
- Reading time
- 4 min
Purchase of a business is the acquisition of an existing business by a company from its owner, called the vendor, under an agreement.
Behavioural objectives
By the end of the lesson, students should be able to:
- Explain the meaning of purchase of a business.
- List and explain the terms used in the purchase of a business account.
- Calculate goodwill or capital reserve from a purchase consideration.
- State how the purchase consideration is paid.
- Draw up a simple business purchase account.
Instructional techniques
- Identification
- Explanation
- Questions and answers
- Demonstration
- Videos from source
Instructional materials
- Videos
- Loudspeaker
- Textbook
- Pictures
What is purchase of a business?
Purchase of a business is the process by which a company takes over an old business and pays the owner an agreed price.
- Vendor: the person who sells the business to the company.
- Purchaser: the company that buys the business.
- Purchase price: the money or shares the purchaser pays to the vendor.
- Agreement: every purchase of a business must have an agreement between the parties.
- Promoters: they can acquire a business and sell it to another company at a profit.
- Price level: a viable business is likely to sell for more than its present value. A business with weak performance may sell for less.
What are goodwill and capital reserve?
Goodwill is the excess of the purchase consideration over the net value of the assets taken over.
- Why goodwill is paid for: the assets, name and customer connections of the business are taken over.
- Revaluation: assets and liabilities are revalued to agreed values before the purchase.
- Trade liabilities: the purchaser can take over trade liabilities as part of the consideration.
- Capital reserve: if the purchase consideration is lower than the net assets, the difference is a capital reserve. It is a gain to the purchaser.
- Liabilities left with the vendor: in some cases the purchaser takes the assets only and the vendor settles the liabilities.
How are goodwill and capital reserve calculated?
- Add up the agreed values of the assets taken over.
- Subtract the liabilities taken over. The result is the net assets.
- Compare the purchase consideration with the net assets.
- If the consideration is higher, the difference is goodwill.
- If the consideration is lower, the difference is capital reserve.
How is the purchase consideration paid?
The purchase consideration can be paid in cash, in shares, or in a mixture of both.
- Cash: the purchaser pays the vendor by bank transfer or cheque.
- Shares: the purchaser issues its own shares to the vendor, at par or at a premium.
- Part cash and part shares: the total of both equals the purchase consideration.
What terms are used in the purchase of a business account?
The business purchase account is a ledger account in the purchaser’s books that brings together the assets, liabilities and price of the business taken over.
- Vendor: the seller of the business, who is paid the purchase consideration.
- Purchaser: the company that buys the business and keeps the account.
- Purchase consideration: the agreed amount the purchaser pays, in cash or shares.
- Assets taken over: items such as premises, stock and debtors, taken at agreed values.
- Liabilities taken over: debts of the old business, such as creditors, which the purchaser agrees to pay.
- Net assets: assets taken over less liabilities taken over.
- Goodwill: the amount by which the consideration is more than the net assets.
- Capital reserve: the amount by which the consideration is less than the net assets.
- Business purchase account: the account used to find the goodwill or capital reserve.
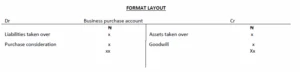
What is the format of the business purchase account?
The business purchase account has two sides, and the balancing figure is goodwill or capital reserve.
| Debit side | Credit side |
|---|---|
| Liabilities taken over | Assets taken over (each one listed) |
| Vendor (purchase consideration) | Goodwill (balancing figure, if any) |
| Capital reserve (balancing figure, if any) |
Journal entries
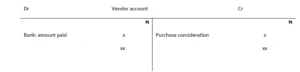
- Debit business purchase account and credit vendor with the purchase consideration.
- Debit each asset account and credit business purchase account with the agreed values.
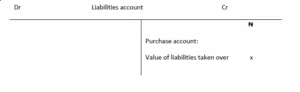
- Debit business purchase account and credit each liability account with the liabilities taken over.
- Debit goodwill and credit business purchase account with any goodwill. For a capital reserve, debit business purchase account and credit capital reserve.
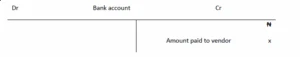
- Debit vendor and credit bank or share capital when the vendor is paid. Credit share premium if shares are issued above par.

What is a worked example of a business purchase?
Ade Ltd buys the business of Mr Bola for ₦800,000 and takes over the creditors.
- Premises: ₦500,000.
- Stock: ₦200,000.
- Debtors: ₦100,000.
- Creditors taken over: ₦80,000.
- Assets taken over: ₦500,000 + ₦200,000 + ₦100,000 = ₦800,000.
- Net assets: ₦800,000 – ₦80,000 = ₦720,000.
- Goodwill: ₦800,000 – ₦720,000 = ₦80,000.
| Debit | ₦ | Credit | ₦ |
|---|---|---|---|
| Creditors | 80,000 | Premises | 500,000 |
| Mr Bola (consideration) | 800,000 | Stock | 200,000 |
| Debtors | 100,000 | ||
| Goodwill | 80,000 | ||
| Total | 880,000 | Total | 880,000 |
Evaluation
- Explain the meaning of purchase of a business.
- List and explain four terms used in the purchase of a business account.
- What is the format of the business purchase account?
- Define goodwill and capital reserve.
- State two ways in which the purchase consideration can be paid.
Classwork: As in the evaluation questions.
Assignment
Chika Ltd buys a business for ₦600,000. The agreed values are premises ₦350,000, stock ₦150,000 and debtors ₦50,000, and creditors of ₦40,000 are taken over. Calculate the net assets and the goodwill or capital reserve, then prepare the business purchase account.
This term's Financial Accounting topics
SS3 First Term · 11 topics
SS3 Financial Accounting Lesson Notes for Other Topics
Nigeria Financial System
Read the full lesson note.
Capital Market I
Read the full lesson note.
Capital Market II
Read the full lesson note.
Loan Capital
Read the full lesson note.

Securities And Exchange Commissions (SEC)
Read the full lesson note.
Nigerian Stock Exchange
Read the full lesson note.
Purchase Of Business Account
Read the full lesson note.

Public Sector Accounting
Read the full lesson note.
Preparation Of Public Sector Accounting
Read the full lesson note.

Hadith 23, 25, & 26 of Imam Nawawi
Read the full lesson note.
Preparation Of Personal Cost Budget
Read the full lesson note.

Branch Account
Read the full lesson note.
Joint Venture Account
Read the full lesson note.
Consignment Account
Read the full lesson note.
Hire Purchase Account
Read the full lesson note.
Lesson Notes for Other Classes

SS1 Lesson Note
The complete lesson note to guide your studies.

SS2 Lesson Note
The complete lesson note to guide your studies.
