
Cost Concept – SS2 Economics Lesson Note (Second Term)
Download this term · ₦1,000Lesson note at a glance
- Subject
- Economics
- Class
- SS2
- Term
- Second Term
- Topic
- Cost Concept
- Order
- Topic 2 of 9 this term
- Reading time
- 6 min
Cost of production is the sum of all payments made to the factors of production used to produce goods and services. The main types are total, fixed, variable, average and marginal cost.
Behavioural objectives
- Define cost of production.
- Explain the economist’s view and the accountant’s view of cost.
- Define total, fixed, variable, average and marginal cost.
- State the formula for each type of cost.
- Calculate the different costs from a simple table of output and cost.
What is cost of production?
Cost of production is the sum of all payments to the factors of production used in producing goods and services.
- Land: receives rent, for example payment for a factory plot.
- Labour: receives wages and salaries, for example pay for bakery workers.
- Capital: receives interest, for example interest on a loan used to buy machines.
- Entrepreneur: receives profit for organising production and taking risks.
- Working together: all four factors must be combined before goods and services can be produced.
How do economists and accountants view cost?
Economists see cost as the alternative given up, while accountants see cost as the money paid.
Economist’s view of cost
- Opportunity cost: the value of the next best alternative given up when a choice is made.
- Scope: it applies to every choice, whether or not money is spent on the item.
- Example: if a person buys a shoe instead of a handset, the opportunity cost is the handset forgone.
Accountant’s view of cost
- Money cost: the total amount of money spent to acquire a product.
- Example: if a trader pays ₦5,000 for a bag, the cost to the accountant is ₦5,000.
Comparison of the two views
| Point | Economist | Accountant |
|---|---|---|
| Meaning of cost | Opportunity cost, the alternative given up | Money spent to acquire a product |
| Measured in | Value of the next best alternative | Naira actually paid |
| Example | The handset forgone when a shoe is bought | The price paid for the shoe |
What are explicit and implicit costs?
Explicit costs are actual money payments, while implicit costs are the value of resources the owner already has and uses.
- Explicit cost: money paid out to others, such as wages, rent and the price of raw materials.
- Implicit cost: the value of the owner’s own resources used in the business, such as a shop he owns or his own time.
- Link to the views: accountants usually count explicit costs, while economists count both.
What are the types of cost?
There are seven cost concepts to learn: total, fixed, variable, average (total), average variable, average fixed and marginal cost.
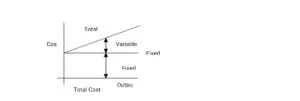
1. Total cost (TC)
- Meaning: the total sum of fixed and variable costs incurred by an enterprise in producing a particular commodity.
- Formula: TC = FC + VC, or TC = AC × Q.
2. Fixed cost (FC)
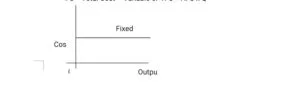
- Meaning: cost that stays constant in the short run, whatever the level of output.
- Other names: overhead cost or unavoidable cost.
- Examples: rent, insurance, salaries of permanent staff.
- Formula: FC = TC – VC, or TFC = AFC × Q.
3. Variable cost (VC)
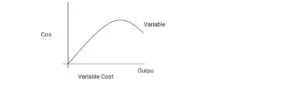
- Meaning: cost of production that changes directly with the level of output.
- Other name: direct cost.
- Examples: raw materials, wages of casual workers, packaging.
- Formula: VC = TC – FC.
4. Average cost (AC) or average total cost (ATC)
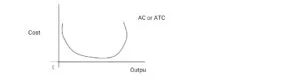
- Meaning: the cost per unit of output.
- How it is found: total cost of a given output divided by the number of units produced.
- Formula: AC = Total cost ÷ Total output, or ATC = AFC + AVC.
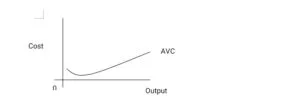
5. Average variable cost (AVC)
- Meaning: the variable cost per unit of output.
- Formula: AVC = TVC ÷ TQ, or ATC – AFC.
6. Average fixed cost (AFC)
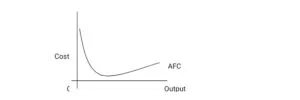
- Meaning: the fixed cost per unit of output.
- Formula: AFC = Total fixed cost ÷ Quantity.
7. Marginal cost (MC)
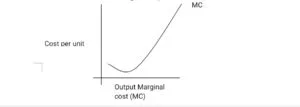
- Meaning: the addition to total cost needed to produce one more unit of output.
- Other name: incremental cost.
- Link to variable cost: it depends only on variable cost, because fixed cost does not vary with output.
- Formula: MC = Change in TC ÷ Change in output.
What are the formulae for the costs?
Each cost has a short formula, listed in the table below.
| Cost | Formula |
|---|---|
| Total cost (TC) | FC + VC, or AC × Q |
| Fixed cost (FC) | TC – VC, or AFC × Q |
| Variable cost (VC) | TC – FC |
| Average cost (AC) | TC ÷ Q, or AFC + AVC |
| Average variable cost (AVC) | VC ÷ Q, or ATC – AFC |
| Average fixed cost (AFC) | FC ÷ Q |
| Marginal cost (MC) | Change in TC ÷ Change in Q |
What is the difference between fixed cost and variable cost?
Fixed cost does not change with output, while variable cost changes directly with output.
- Fixed cost: a cost such as rent that must be paid even when nothing is produced.
- Variable cost: a cost such as raw materials that rises as more is produced.
| Point | Fixed cost | Variable cost |
|---|---|---|
| Effect of output | Stays the same | Rises as output rises |
| When output is zero | Still has to be paid | Is zero |
| Other name | Overhead cost | Direct cost |
| Examples | Rent, insurance | Raw materials, casual wages |
How are the costs worked out from a table?
Each cost is worked out from output, fixed cost and variable cost using the formulae above.
- Illustration: a small bakery has a fixed cost of ₦120 and the variable costs shown below (figures are for practice only).
| Output (Q) | FC (₦) | VC (₦) | TC (₦) | AFC (₦) | AVC (₦) | AC (₦) | MC (₦) |
|---|---|---|---|---|---|---|---|
| 1 | 120 | 60 | 180 | 120 | 60 | 180 | 60 |
| 2 | 120 | 100 | 220 | 60 | 50 | 110 | 40 |
| 3 | 120 | 150 | 270 | 40 | 50 | 90 | 50 |
| 4 | 120 | 240 | 360 | 30 | 60 | 90 | 90 |
Steps used
- Add FC and VC to get TC. For Q = 2, 120 + 100 = 220.
- Divide FC by Q to get AFC. For Q = 2, 120 ÷ 2 = 60.
- Divide VC by Q to get AVC. For Q = 2, 100 ÷ 2 = 50.
- Divide TC by Q, or add AFC and AVC, to get AC. For Q = 2, 60 + 50 = 110.
- Find the change in TC for each extra unit to get MC. From Q = 2 to Q = 3, 270 – 220 = 50.
What the table shows
- FC: stays at ₦120 at every level of output.
- AFC: falls as output rises, because the same fixed cost is shared among more units.
- MC: equals the rise in VC, since FC does not change.
- AVC: falls from ₦60 to ₦50, then rises back to ₦60 as output grows.
- MC and AC: at Q = 4, MC is ₦90 and AC is ₦90, so MC has risen to meet AC.
What is a second worked example?
A firm has a fixed cost of ₦500 and produces 100 units at a variable cost of ₦1,500.
- Find TC: 500 + 1,500 = ₦2,000.
- Find AFC: 500 ÷ 100 = ₦5.
- Find AVC: 1,500 ÷ 100 = ₦15.
- Find AC: 2,000 ÷ 100 = ₦20, which also equals 5 + 15.
How do the average and marginal costs behave as output rises?
AFC keeps falling as output rises, while AVC, AC and MC usually fall first and then rise.
- AFC: falls continuously, because fixed cost is spread over more units.
- AVC and AC: fall at first, reach a lowest point, then rise as the cost of extra units increases.
- MC: usually falls at first, then rises.
- Meeting point: MC cuts the AVC and AC curves at their lowest points.
Evaluation
- Define cost of production.
- Explain the difference between the economist’s view and the accountant’s view of cost.
- State two examples each of fixed cost and variable cost.
- Write the formula for average total cost and for average variable cost.
- Why does marginal cost not depend on fixed cost?
Assignment
- Define total cost and marginal cost, write the formula for each, and explain opportunity cost with an example of your own.
This term's Economics topics
SS2 Second Term · 9 topics
Get Economics as PDF and Word
Every week of SS2 Economics, Second Term, formatted and ready to print. Ad-free, and the copy lock comes off.
Get this term Card, bank transfer, USSD or OPay
SS2 Economics Lesson Notes for Other Topics
Production Possibility Curve
Read the full lesson note.
Revenue Concept
Read the full lesson note.
Economics System
Read the full lesson note.
Labour Market
Read the full lesson note.
Supply And Demand Of Labour
Read the full lesson note.

Market Structure
Read the full lesson note.
Imperfect Market
Read the full lesson note.

Industries In Nigeria
Read the full lesson note.
Basic Tools For Economic Analysis
Read the full lesson note.
Measures Of Dispersion
Read the full lesson note.
Theory Of Consumer Behaviour
Read the full lesson note.

Demand And Supply
Read the full lesson note.
Elasticity Of Demand
Read the full lesson note.
Income Elasticity Of Demand
Read the full lesson note.
Cross Elasticity Of Demand
Read the full lesson note.
Lesson Notes for Other Classes

SS1 Lesson Note
The complete lesson note to guide your studies.
SS3 Lesson Note
The complete lesson note to guide your studies.
