
Farm Records and Accounts – SS3 Agricultural Science Lesson Note (Second Term)
Download this term · ₦1,000Lesson note at a glance
- Subject
- Agricultural Science
- Class
- SS3
- Term
- Second Term
- Topic
- Farm Records and Accounts
- Order
- Topic 5 of 5 this term
- Reading time
- 8 min
Farm records and accounts are the written documents and money statements that show the activities and finances of a farm business.
Behavioural objectives
By the end of the lesson, students should be able to:
- define farm records and farm accounts;
- state the importance of keeping farm records and accounts;
- list and describe the types of farm record and farm account;
- prepare a simple profit and loss account;
- define common accounting terms such as assets, liabilities, liquidity, solvency, appreciation and depreciation;
- calculate total depreciation, annual depreciation and salvage value.
What are farm accounts and farm records?
A farm record is a written document showing the major activities going on in a farming business.
- Farm record: written document of the major activities on the farm, such as daily work, yields and labour.
- Farm account: statement of money paid out or received for goods and services used in the farming business.
Why are farm accounts and records important?
Farm records and accounts help the farmer to monitor prices, work out profit, show the financial position of the farm and plan for the future.
- Price monitoring: shows changes in the prices of products bought or sold.
- Financial position: shows how well off the farm is at a given time.
- Profit: helps to determine the profit or loss made.
- Fraud: helps to detect theft and fraud.
- Decisions: helps in making informed management decisions.
- Loans: banks and lenders ask for them when a farmer applies for a loan.
- Tax: used to determine annual tax.
- Farm worth: helps to determine the actual worth of the farm.
- Management efficiency: used to compare how well farms are managed.
- Enterprise performance: used to evaluate the performance of each enterprise, such as poultry or maize.
- Future returns: helps to estimate future farm returns.
- Research: provides a basis for conducting research.
- Health monitoring: helps to monitor the health status of crops and animals.
What are the types of farm record?
There are six types of farm record: farm diary, farm inventory, sales and purchase record, yield record, payroll record and input utilisation record.
- Farm diary: record of daily activities on the farm.
- Farm inventory: list of all assets on the farm and their money worth or value.
- Sales and purchase record: record of revenue and expenses made by the farm business.
- Yield or production record: information on the output of crops and animal products.
- Payroll or labour record: amount and types of labour hired, and the rate at which wages are paid.
- Farm input utilisation record: inputs required, inputs used and the level of input application.
What are the types of farm account?
There are seven types of farm account: sales, purchase, farm valuation, cash analysis, farm income statement, balance sheet and profit and loss account.
- Sales account: also called the sales and receipt account. It shows the produce sold, the quantity, the date, the buyer and the price.
- Purchase account: shows the items bought for use on the farm.
- Farm valuation: value of the farm at the start and end of production. The first is the opening valuation and the second is the closing valuation.
- Cash analysis account: details of the income and expenditure of the farm over a given period.
- Farm income statement: all farm receipts (sales) and expenses over a period of time.
- Balance sheet (net worth statement): shows the capital or financial position of the farm at the end of the accounting period, usually a year.
- Profit and loss account: prepared at the end of the business year to show whether the farm made a profit or a loss.
What is a profit and loss account?
A profit and loss account is a statement that compares the income of a farm with its expenses at the end of the business year.
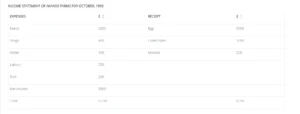
- Debit side (left): all expenses and purchases, and the opening valuation.
- Credit side (right): all receipts from sales, and the closing valuation.
How do you prepare a profit and loss account?
- Write the name of the farm and the period, for example “for the year ended 31/12/17”.
- List the opening valuation, expenses and purchases on the debit side.
- List the sales, produce used at home and closing valuation on the credit side.
- Add up each side.
- Subtract the debit total from the credit total. A higher credit total gives a net profit. A higher debit total gives a net loss.
Why is the profit and loss account important?
- Profit or loss: shows whether the farm is making a profit or a loss.
- Performance: shows the overall performance of the farm at the end of the accounting period.
- Planning: aids future planning of the farm for better results.
Example: profit and loss account for Segun Farms
Prepare a profit and loss account for Segun Farms for the year which ended 31/12/17, using the following data:
- Cost of feed: ₦500
- Cost of drugs: ₦200
- Sales of eggs: ₦2000
- Eggs for domestic use: ₦200
- Loss due to mortality: ₦300
- Value of stock left: ₦600
- Farm wages: ₦400
- Sales of spent layers: ₦1000
- Transportation costs: ₦300
- Depreciation: ₦200
- Electricity bill: ₦300
- Net profit: ₦1600

| Debit side | ₦ | Credit side | ₦ |
|---|---|---|---|
| Feed | 500 | Sales of eggs | 2000 |
| Drugs | 200 | Eggs for domestic use | 200 |
| Loss due to mortality | 300 | Sales of spent layers | 1000 |
| Farm wages | 400 | Closing valuation (stock left) | 600 |
| Transportation | 300 | ||
| Depreciation | 200 | ||
| Electricity | 300 | ||
| Total expenses | 2200 | Total receipts | 3800 |
| Net profit | 1600 |
- Check: ₦3800 minus ₦2200 = ₦1600 net profit.
What are the common accounting terms?
Accounting terms are the words used to describe the property, costs, debts and worth of a farm business.
What is a farm asset?
A farm asset is anything of value in the possession of a farm business. There are two types: fixed assets and current assets.
- Fixed assets: assets not used up during production, such as land, farm buildings, motor vehicles, tools, incubators and milking machines.
- Current assets: assets used up during production, such as water, feed, drugs, chemicals, fertilisers, seeds and cash in the bank.
| Point | Fixed assets | Current assets |
|---|---|---|
| Use in production | Not used up | Used up |
| Life | Last for many years | Used within a short time |
| Examples | Buildings, tractor, incubator | Feed, seeds, fertiliser, cash in bank |
What are fixed and variable costs?
Costs are the expenses made during production. There are two types: fixed cost and variable cost.
- Fixed cost: part of total production cost that does not vary with the level of production, such as buildings, equipment, machinery and structures like a silo or barn.
- Variable cost: part of total cost that varies directly with the level of production, such as wages, salaries, seeds, fertilisers and agrochemicals.
| Point | Fixed cost | Variable cost |
|---|---|---|
| Effect of output | Stays the same when output changes | Rises and falls with output |
| Examples | Farm buildings, machinery, silo | Wages, seeds, fertiliser, agrochemicals |
What are liabilities?
Liabilities are money owed to outside persons or bodies, for example a bank loan. There are two types.
- Current or short-term liabilities: debts that must be paid back within one accounting year.
- Long-term liabilities: debts that cannot be paid within one accounting year.
What is net capital, net worth or owner equity?
Net capital (net worth or owner equity) is the total amount of money supplied by the owner of the farm business.
- Formula: assets minus liabilities = owner’s equity (capital).
What are the other accounting terms?
- Liquidity: ability of a farm business to meet its financial obligations as they fall due. It is also the ease of turning assets into cash.
- Solvency: ability of the farm business to pay off all its debts. A farm is solvent if selling its assets would cover all its debts.
- Appreciation: increase in the value of an asset over time, as with growing animals, cash crops and land.
- Depreciation: loss or reduction in the value of an asset as it is used over time.
- Salvage value: amount at which an asset is sold off when it is no longer economical to keep, or when maintenance costs are too high.
- Useful life span: number of years a piece of farm equipment can effectively serve the farmer.
How do you calculate depreciation and salvage value?
Depreciation is calculated by spreading the loss in value of an asset equally over its useful life span.
- Total depreciation = cost price of asset minus salvage value of asset.
- Annual depreciation = total depreciation ÷ useful life span (in years).
Example
A plough was bought in 1985 at a cost of ₦6000 and sold off in 1990 for ₦1000. Calculate the salvage value, total depreciation, annual depreciation and appreciation.
Solution
- Cost price: ₦6000.
- Salvage value: ₦1000.
- Useful life span: 1990 minus 1985 = 5 years.
- Salvage value = ₦1000, the price at which it was sold off.
- Total depreciation = cost price minus salvage value = ₦6000 minus ₦1000 = ₦5000.
- Annual depreciation = ₦5000 ÷ 5 = ₦1000.
- Appreciation: a plough loses value with use, so there is no appreciation.
Evaluation
- What are farm records and accounts? List five reasons for keeping them.
- List five types of farm record and explain any two.
- List five types of farm account and explain the profit and loss account.
- Define (i) appreciation, (ii) solvency and (iii) liquidity.
- Distinguish between fixed assets and current assets, and between fixed and variable costs.
Assignment
Read Chapter 48 of Essential Agricultural Science for Senior Secondary School by O.A. Iwena, pages 440 to 449, then answer the questions below.
- Textbook: questions 3, 4, 6 and 9 on page 448.
- WAEC past questions (theory): 1989 question 10, 1993 question 10, 1996 question 10, 1997 question 10 and 1998 question 10.
- More WAEC past questions (theory): 2013 questions 9 and 10, 2009 questions 9 and 10, 1999 question 9, 2006 question 9 and 2007 question 9.
This term's Agricultural Science topics
SS3 Second Term · 5 topics
Get Agricultural Science as PDF and Word
Every week of SS3 Agricultural Science, Second Term, formatted and ready to print. Ad-free, and the copy lock comes off.
Get this term Card, bank transfer, USSD or OPay
SS3 Agricultural Science Lesson Notes for Other Topics

Agricultural Marketing
Read the full lesson note.
Agricultural insurance
Read the full lesson note.

Animal Disease
Read the full lesson note.

Animal Diseases II - Bacteria, Fungal & Protozoan Diseases
Read the full lesson note.
Agricultural Extension
Read the full lesson note.

Agricultural Extension II
Read the full lesson note.
Aquaculture
Read the full lesson note.
Aquaculture II - Fishing Gear & Crafts
Read the full lesson note.
Animal Improvement
Read the full lesson note.
Artificial Insemination
Read the full lesson note.
Agricultural Financing
Read the full lesson note.
Agricultural finance II
Read the full lesson note.
Lesson Notes for Other Classes

SS1 Lesson Note
The complete lesson note to guide your studies.

SS2 Lesson Note
The complete lesson note to guide your studies.
